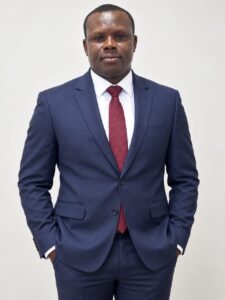

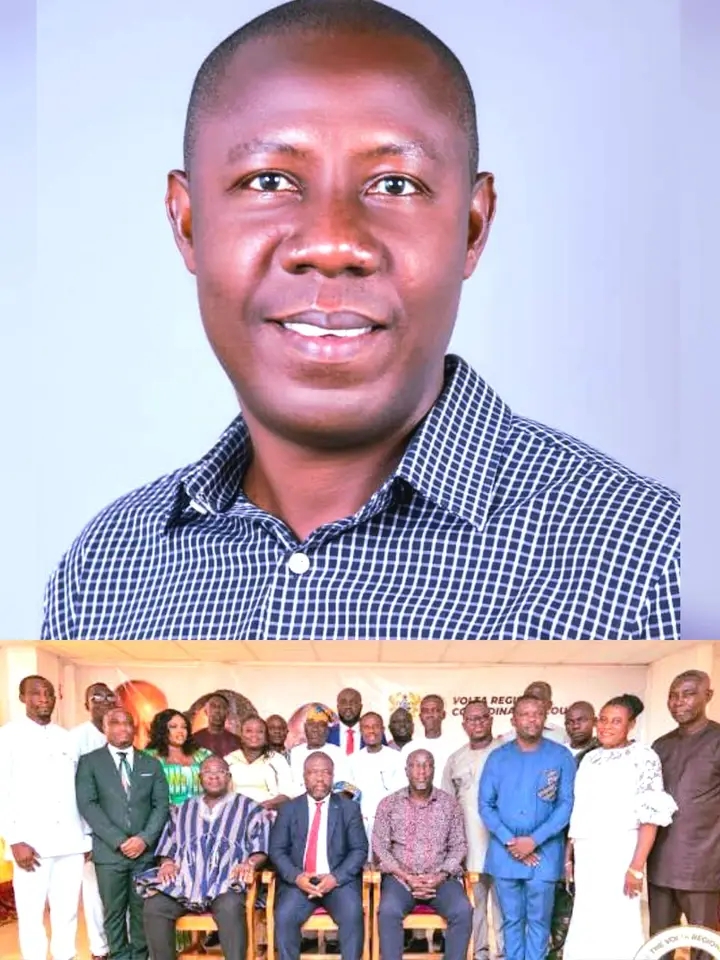
In a direct challenge to the primary drivers of local governance, prominent financial administrator Yao Amekor has called on Metropolitan, Municipal & District Chief Executives (DCEs) across the Volta and Oti regions to aggressively back local Community Banks, labeling them the area’s most lucrative, yet severely underutilized, development assets.
Writing in his personal capacity, Amekor who serves as a Director of Agave Community Bank Plc, Vice President of the Volta/Oti Chapter of the Association of Rural Banks, and a Director of ARB Apex Bank Plc warned that the shared socio-economic progress of these regions will remain stalled as long as political leaders keep personal and state-allocated capital in commercial banks headquartered outside their economic enclaves.
The intervention comes at a critical juncture as Bank of Ghana is currently enforcing a sweeping recapitalization agenda, lifting the minimum stated capital requirement for rural and community banks from Gh¢1 million to Gh¢5 million. Rather than viewing this as a regulatory hurdle, Amekor frames it as a historic opportunity for local governance leaders to permanently fortify the economic foundations of their districts.
*️⃣ A Direct Call to Accountability for MMDCEs *️⃣
Amekor’s message to newly and former District Chief Executives, alongside Members of Parliament of Ghana, cuts through traditional political rhetoric. He asserts that DCEs, who are constitutionally mandated to drive grassroots development and district growth, cannot claim to champion economic empowerment while remaining detached from the local financial institutions that fund it daily.
“This is not a rhetorical question. It is an accountability question,” Amekor stated, challenging DCEs to declare their personal and institutional stakes in the 14 community banks anchoring the region. “For too long, community banking has been treated as the concern of ordinary depositors and small savers, while those with the greatest resources, networks, and platforms have kept their money elsewhere.”
To bridge this gap, Amekor outlines four concrete pathways for genuine participation by political and administrative leaders:
1️⃣ Direct Capital Injection: Acquiring equity shares to directly strengthen the banks’ capital bases while earning real financial returns.
2️⃣ Governance Support: Stepping onto boards to inject professional expertise and strategic oversight where it is most urgently needed.
3️⃣ Public Advocacy: Utilizing the high-profile platforms of the DCE office to normalize and promote community banking as a premier economic choice.
4️⃣ Institutional Patronage: Deliberately routing personal, business, and assembly-related banking relationships into local institutions to prevent capital flight.
*️⃣ The Untapped Opportunity: Over 50% Returns on Equity*️⃣
Demolishing the misconception that community banks are mere charity-driven micro-financiers, Amekor revealed that well-governed institutions within the Volta and Oti sectors are among the most compelling investment vehicles in the regional economy.
“What many people do not yet appreciate is that well-governed Community Banks can generate exceptionally strong financial returns,” Amekor noted. “Some institutions within this sector have consistently delivered returns on equity exceeding 50 percent year-on-year, while simultaneously driving tangible development outcomes.”
These fourteen institutions strategically spanning major agrarian and trading hubs are legally structured to reinvest wealth directly into the local economy. In the southern and central belts, this financial network is anchored by Agave Community Bank in Dabala, Anlo Community Bank in Anloga, Avenor Community Bank in Akatsi, Mepe Area Community Bank in Mepe, Amuga Community Bank in Adidome, and Unity Community Bank in Ziope. Moving further into the mid-Volta and northern territories, the sector’s reach extends through Weto Community Bank in Kpeve, Frerol Community Bank in Kpando, Butawu Community Bank in Tsito-Awudome, and Gbi Community Bank in Hohoe. The northern clusters and Oti enclave are similarly fortified by North Volta Community Bank in Guaman, Kaakye Community Bank in Kete-Krachi, Kpassa Community Bank in Kpassa, and Asubongteng Community Bank in Worawora, ensuring comprehensive regional coverage.
By underwriting high-risk local sectors such as agricultural credit for smallholders, SME loans for traders, and transport operator financing, these banks create jobs and circulate wealth where commercial giants refuse to tread.
*️⃣ A Mandate for Actionable Growth*️⃣
The policy brief concludes with a call to action for leadership to move past the era of simply holding a savings account. With the Bank of Ghana’s regulatory shift actively encouraging stronger capitalization, the infrastructure for genuine regional independence is already in place.
“Strong local banks build the kind of economic independence that no government transfer or donor program can sustainably replace,” Amekor emphasized. “The institutions exist. The returns are real. The development case is undeniable. The only question is whether those with the greatest capacity to act will choose to do so.”
SRHR: Peter Dzorgbenyuie Junior Narteh-Agbeyome – Content Creator